Longtime PFS member and economist Saifedean Ammous, author of The Bitcoin Standard and a critic of Javier Milei, debated Argentine economist Iván Carrino, who defends the Milei government. The debate took place at LABITCONF in Buenos Aires on October 30, 2026, and Yayi Morales moderated.1
Ammous argues that Milei did a “complete 180” on his own campaign. He kept the central bank, and the money supply has grown four- to fivefold. The debt has grown by about $60 billion, even after a 77% devaluation that amounted to a stealth default on peso debt. Meanwhile a peso-bond “carry trade” keeps the whole thing going and starves the productive economy of capital. Carrino concedes that Milei’s program isn’t Austrian and that money growth was too high early on. But he credits Milei with real spending cuts, deregulation, trade opening, a 178-point drop in annual inflation and slower money growth. He blames most of the debt increase on capitalized interest on zero-coupon bonds. Neither persuaded the other. A detailed summary follows the video, followed by related posts and material.
From Saifedean Ammous and Iván Carrino, “352. Debating Milei’s Economic Policies in Argentina,” The Bitcoin Standard Podcast (LABITCONF, Buenos Aires, Oct. 30, 2026):
1. Ammous’s Opening
Ammous says he was thrilled when Milei ran for president. He had seen Milei on TV making arguments he mostly agreed with, and here was a libertarian anarchist with a real chance to show the world how free-market ideas work. He was disappointed almost at once. This was not a case of the good being the enemy of the perfect, he says. It was a “complete 180” from both the Austrian agenda and Milei’s own campaign.
Argentina’s problems, he argues, come down to money printing and government debt. The state borrows, prints money to pay its debts, and then either the currency collapses or the state seizes bank deposits. Milei ran on ending that cycle, then changed his rhetoric and his actions once elected. The central bank is still there, and debt has risen by about $61 billion on his watch. That happened even as the peso lost about 77% of its value. Roughly half the debt was in pesos, so the devaluation cut its dollar value by around $110 billion. Ammous calls that an effective default and a huge gift to the government. Counting it, total borrowing under Milei comes to something like $170 billion in under three years.
Worse, he says, every measure of the money supply is up 300–400% and growing 4–5% a month. That may be the most expansionary monetary policy of any Argentine government, which is saying something. (Argentines, he jokes, are world champions at inflation, football and beef.) Prices keep rising as a result, and Argentina still has some of the highest price inflation in the world.
Why is the money supply growing when the government runs a primary surplus? Because, he says, the government is running a “carry trade,” “a Ponzi scheme essentially,” in peso debt that pays around 2% a month. The market for these bonds is now about three times the size of the Argentine stock market. Few businesses can match those yields, so capital that should go into productive firms goes to the government instead. As long as the government holds the exchange rate below the bond yield, the scheme keeps growing. That means more liabilities, more money creation and more price increases: more debt, more inflation, and nothing changes.
2. Carrino’s Rebuttal
Carrino takes up Ammous’s three charges: money creation, rising debt, and not being Austrian enough. He agrees that Milei’s policy is far from the Austrian tradition. But he argues that its core (fiscal austerity, deregulation and opening to trade) is standard classical-liberal fare that Austrians would endorse.
On inflation, he concedes that cumulative inflation since 2023 is the highest of the last five presidencies. The better measure, he says, is the change in the annual rate, which has fallen by 178 percentage points. He calls that the biggest drop since the hyperinflation of the ’90s. True, Milei hasn’t abolished the central bank. But Carrino says that doesn’t make him un-Austrian, because Mises and Hayek, in his telling, never proposed eliminating it. He also agrees that the monetary aggregates have grown four- or fivefold, a criticism he says he has made himself. But their annual growth is now the lowest since 2009, which he calls “very prudent” monetary policy.
On debt, he accepts the figure of roughly $60 billion from Argentina’s finance ministry but points to spending. Spending is down 28% in real terms and has stayed there for three years. Pensions were cut only 2% in real terms, capital spending is 77% below 2023, and 70,000 public employees have been laid off. The ministry’s own figures, he says, show that debt retired exceeds new debt issued by about $33 billion. A Kirchnerite government would show the opposite: new borrowing to fund spending. The increase comes instead from capitalized interest on the zero-coupon bonds now used to roll over old debt, which don’t book interest separately. It’s a technical point, he says, but it shows the government is neither hiding numbers nor failing to shrink the state. Given its constraints, he concludes, Milei’s government is pursuing a healthy policy that could make Argentina “a normal country,” and in the best case a prosperous one.
3. Moderator’s Questions
Morales asked Ammous whether he was being too demanding, given Argentina’s political constraints and a century of Keynesian policy. Ammous replies that Milei campaigned on closing the central bank as “non-negotiable” and won. That gave him the political capital to at least try, yet he made no attempt from day one. Even with the central bank left in place, Milei could have dollarized, or kept the peso and simply stopped inflating. “Inflation is a choice,” Ammous says: someone has to click print. Instead Milei followed the same formula as Macri. He printed, borrowed, said what markets wanted to hear, and spoke “the IMF language” to get more loans and kick the can down the road.
Asked whether Milei should change course or Argentina needs a different government, Ammous says Argentina needs to stop printing and borrowing, whoever does it. Spending cuts matter, but not while interest on peso bonds keeps piling up. Nearly three years in, the painful part should be over. Ecuador, he notes, had low inflation within two years of dollarizing. He expects more pain ahead.
Asked when political constraints become an excuse, Carrino notes that Milei asked Congress to let him privatize 40 companies and got two. That’s on the legislature, he says. Money printing, though, is the executive’s decision, so on that point the criticism is “legitimate.” He adds that Milei inherited a pressure cooker of price controls and pent-up inflation and took the lid off. He freed the exchange rate and the subsidized prices of electricity and gas. The remaining exchange controls, Carrino says, “should be eliminated yesterday,” though he thinks they matter little.
The peso debt is growing, he argues, because of zero-coupon rollovers, not deficits. It also grows because Argentina is “finally” paying savers a positive real interest rate, which he calls an Austrian policy. Since inflation runs above the rate of devaluation, the peso debt grows in dollar terms. And the strong peso reflects record exports of oil, minerals and farm goods, now that exporters are no longer punished.
4. Direct Exchange
Inflation. Ammous says the early inflation spike came from Milei’s own huge devaluation, which cut the government’s liabilities by 70–80% within months. Slowing the printing afterward was the natural next step, not a miracle, yet every comparison is made against that one outlier. Lebanon got inflation down to about 10% after its hyperinflation, despite war, collapsing infrastructure, no electricity and a broken banking system. Argentina is still at about 30% three years in, and only continued printing explains that. Carrino replies that the spike wasn’t an outlier. It was inflation hidden by price controls that surfaced in 2024. Today’s 30% is “not great,” he says, but it’s the lowest in a decade. He grants that dollarization would have meant 2% inflation, but says it has costs.
Bonds and default. Ammous says paying a positive return on loans to the Argentine government just pulls capital away from productive use. Lending to that government, he says, is “one of the worst investments in human history” (“I agree,” says Carrino). Carrino asks what the alternative is: “Reject the debt? Just not pay it?” Pay 10% when inflation is 33%, he says, and Argentina defaults and no one lends to it again. High rates are the price of past misbehavior and, he hopes, temporary.
Ammous answers that the zero-coupon debt is real. It is added to the balance sheet and is no different from spending. He calls it politically fatal for free-market ideas in Latin America that governments break their contracts with employees, teachers, firefighters and ordinary peso holders by paying them in devalued currency, while treating bondholders as sacred. In fact, he says, the 77% devaluation already was a default on peso bonds. The government could have gone a little further, paid off the debt and stopped borrowing. Instead it hid the cost in zero-coupon debt to keep a lucrative speculative game going. Dollar wealth flows to the winners of the carry trade while ordinary Argentines watch their pesos lose value.
Carrino counters that firing a government employee or canceling a public works contract isn’t a default. He recalls 2001, when President Adolfo Rodríguez Saá defaulted in the name of paying teachers. Country risk hit 7,000 points and financing dried up. The printing press and Kirchnerism followed, with cumulative inflation of perhaps 1,000–2,000%, he says. Balancing the budget, in his view, attacks both country risk and inflation. He adds that total spending, interest included, is down about 30% in real terms. The IMF puts the deficit at 0.8% of GDP when the capitalized interest is counted, against 5–6% in the past. The state is also smaller in regulation, export taxes and import restrictions. He dislikes many of Milei’s non-economic policies, he says, but on economics a free-market libertarian should see movement in the right direction.
Ammous says only the money supply and the debt really matter. Debt binds people to decades of taxes, and inflation destroys wealth and economic calculation. In a few years, he predicts, Argentina will be back where it started, with a new president promising reforms. And because Milei promised what Argentina needs and then did the opposite, the next person who promises it won’t be believed.
Refinancing and recovery. Carrino asks whether inflation will fall now that base money (M0) is growing only about 6% a year. Ammous says that’s hard to tell, given all the pesos created for the carry trade, but he sees no way out without either a massive devaluation or a default. Carrino asks why Argentina can’t keep rolling over its debt the way the US and France do, unless Kicillof wins. Ammous says a final crisis isn’t certain, but kicking the can with ongoing devaluation does harm too. Carrino says there is no devaluation now: the exchange rate has been stable for about a year and a half. Ammous says that’s only because the central bank is managing the rate while it expands the money supply.
And if this is the path forward, Ammous asks, why is there no recovery after three years? Inflation is still high and country risk is around 750. GDP, employment and industrial output are getting worse. Economics is about real resources, he says, not numbers “made up by economists and by scammers like the IMF.” Carrino gets the last word. Industrial output is falling, he says, because manufacturing has lost 70 years of tariff protection and now pays the real price of electricity. Whole sectors now have to face reality.
5. Closing Remarks
Ammous says nobody has disputed his main points. Debt is up, the money supply is up, and the chance for monetary reform was missed, a costly mistake Argentina will pay for. The radical Austrian idea of escaping “central bank slavery,” he says, was used to win votes and to convince the IMF and other lenders that something different was coming. In reality it’s business as usual: borrow, print, and leave the problem to the next generation of politicians.
Carrino says the debt has risen in dollar terms for technical reasons. But the standard sustainability test, which compares the interest rate with the growth rate, shows debt-to-GDP falling and then holding steady over three years. Money creation was too high at first but is now at its lowest level in years. Together with the budget surplus, he says, that points to falling inflation. He is optimistic, as long as the course isn’t abandoned.
Morales closes by saying that Argentina has made significant changes, but many questions remain.
Related
- Saifedean Ammous, “Javier Milei’s Austrian Scam By the Numbers,” Property and Freedom Journal (May 18, 2026). This is the written version of Ammous’s case in the debate. The money aggregates tripled or quadrupled in 29 months, growing about 5% a month. April’s CPI rose 2.6% for the month (31% annualized). And Argentina is now the IMF’s largest borrower, at about 35% of its lending.
- Hans-Hermann Hoppe, “Javier Milei” (PFS 2024), HansHoppe.com (Oct. 1, 2024). This is Hoppe’s original critique at the 2024 PFS meeting in Bodrum. Its central charge, that Milei broke his promise to abolish the central bank, is the same one Ammous presses here.
- Hans-Hermann Hoppe, “A ‘Great Thinker’ at Work,” HansHoppe.com (June 13, 2025). Hoppe takes apart Milei’s claims that closing the central bank would cause hyperinflation and that the paper peso is government debt. That bears on the debaters’ argument over whether Milei had to keep the central bank.
- Hans-Hermann Hoppe, “Milei in Madrid – Again, Messing up….” (Oct. 25, 2026). At the Madrid Conference on Austrian Economics, Milei called Spain’s prime minister a dictator and a thief. Hoppe argues the same charges fit Milei, starting with his inflation record.
- Tom DiLorenzo, “Milei ‘hearts’ the IMF and embraces Keynesian Demand Management” (Nov. 5, 2026). The IMF is about to approve a review that clears another $900 million for Milei’s government. Compare Ammous’s charge that Milei speaks “the IMF language” to keep the loans coming.
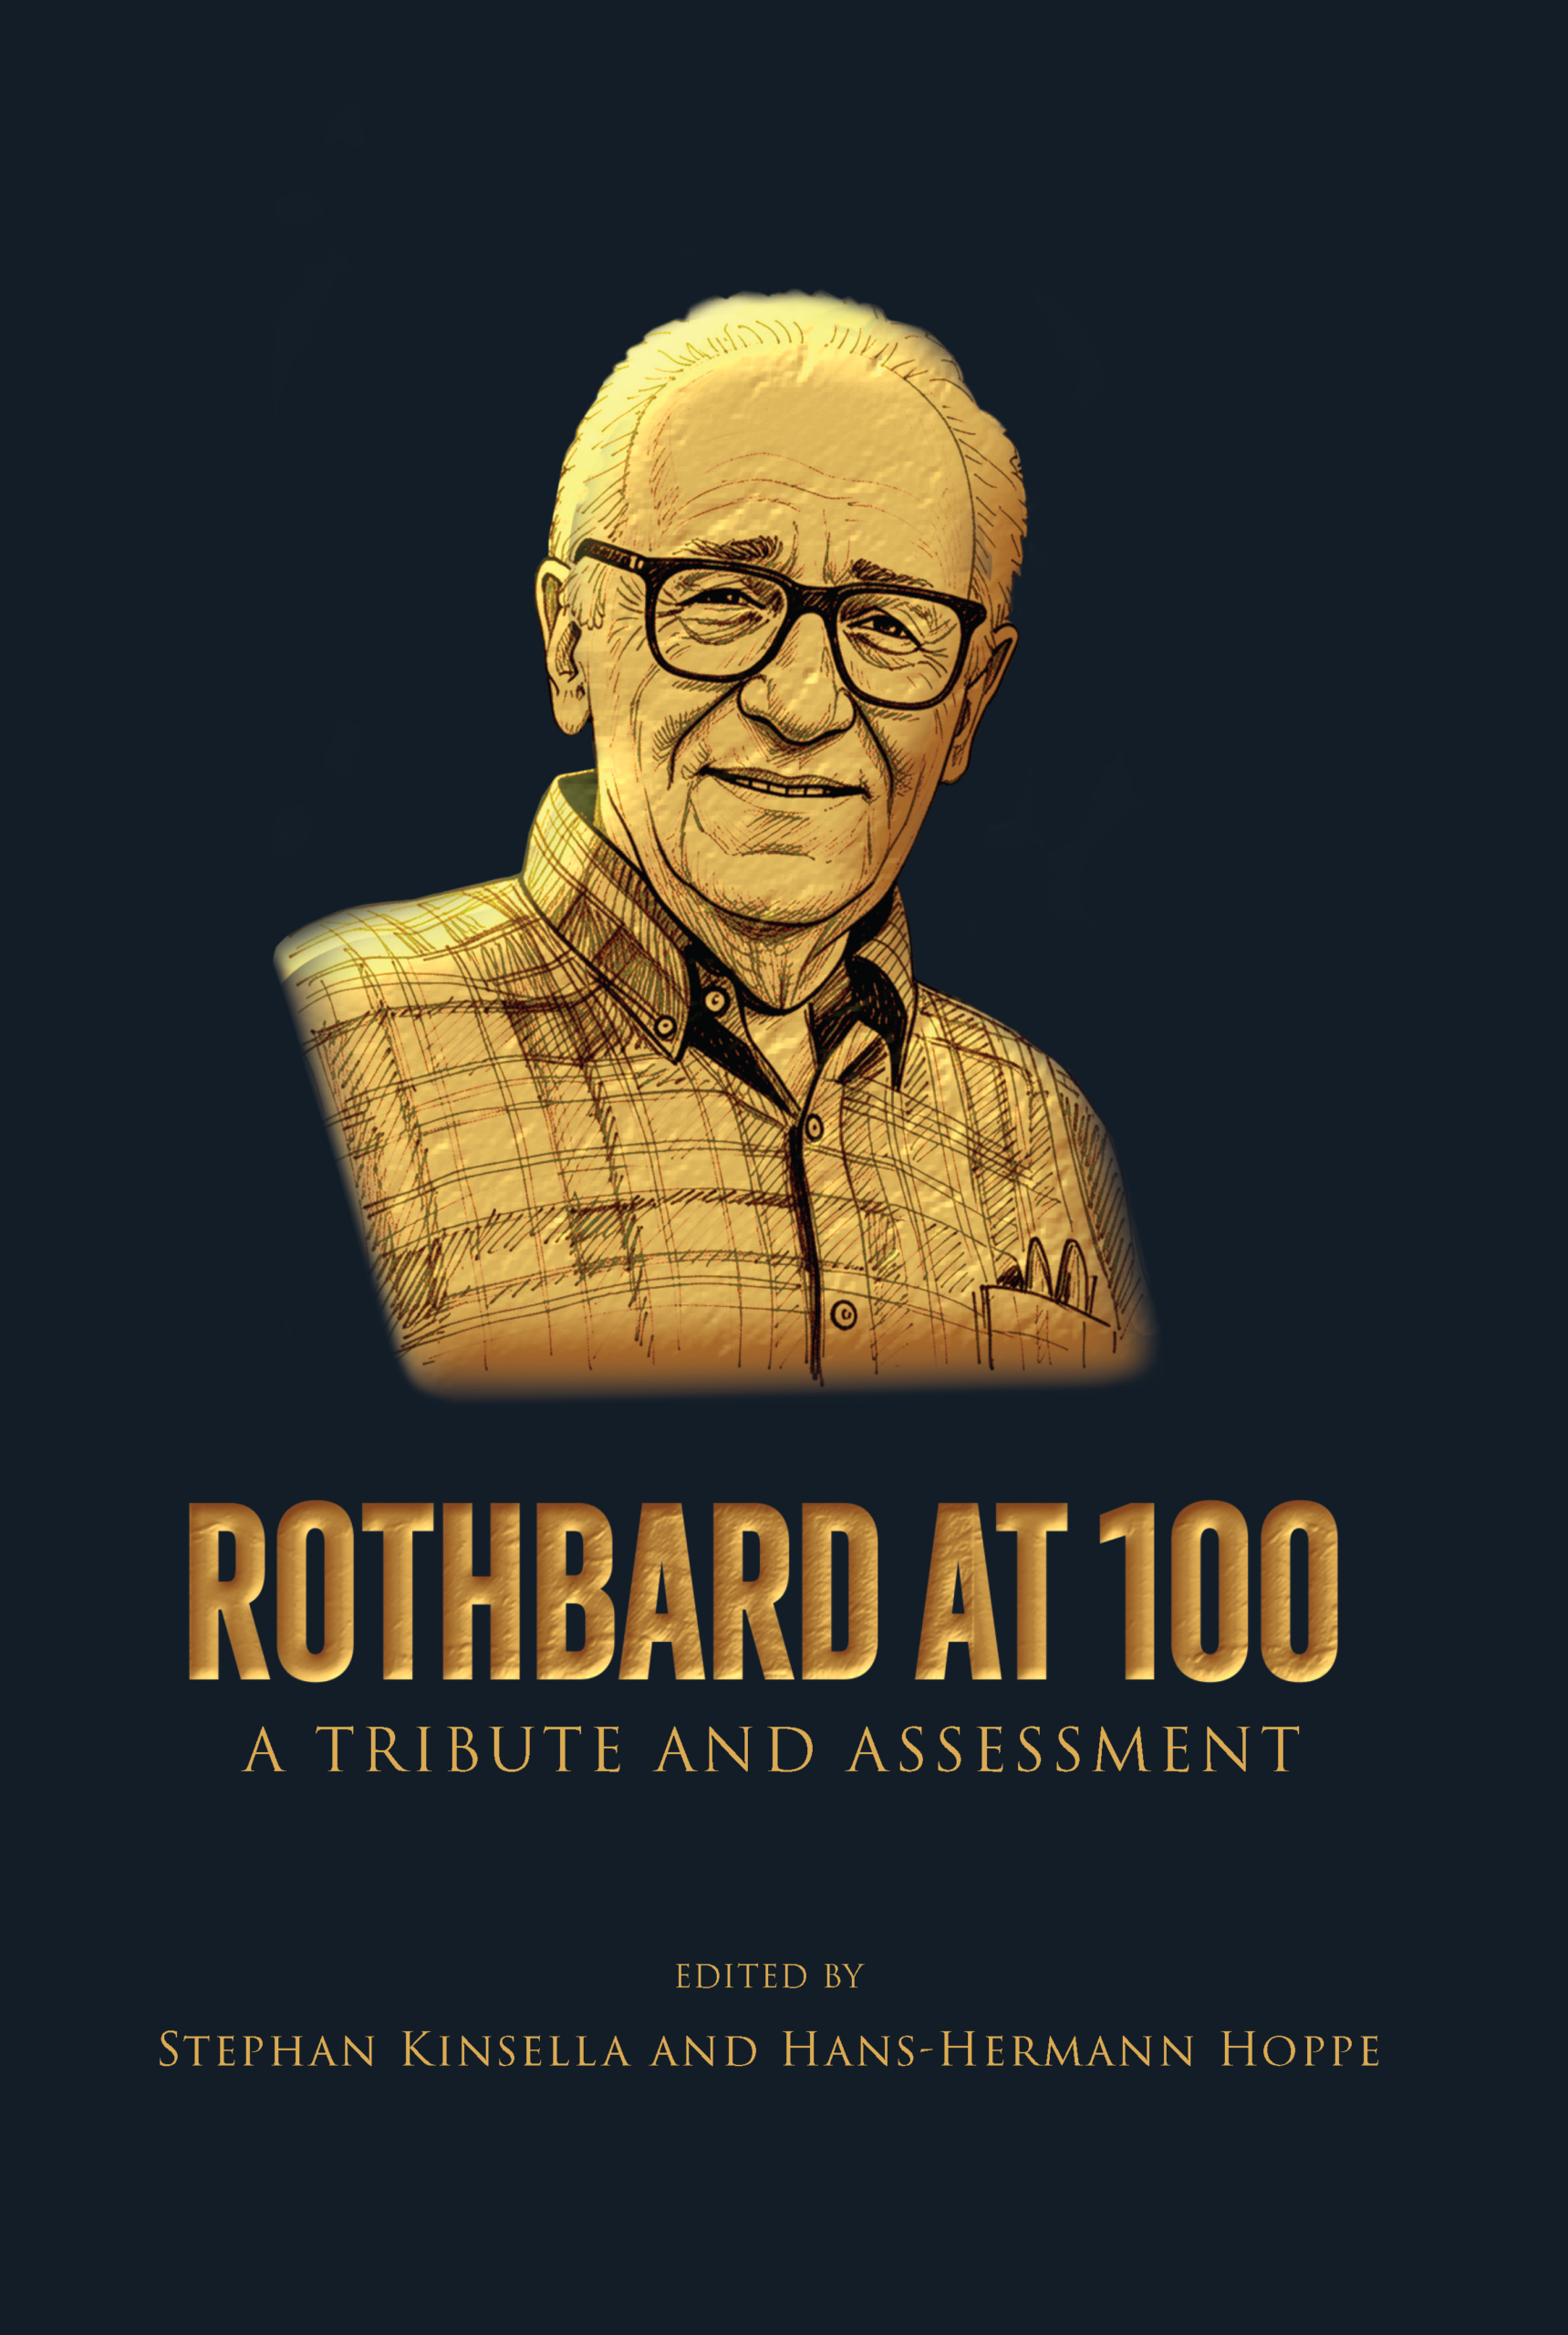
- Stephan Kinsella, “Unlike Milei, and per Rothbard, Repudiate the Debt!,” StephanKinsella.com (Feb. 8, 2026). Carrino asks, “Reject the debt? Just not pay it?” Rothbard and Chodorov said yes. The post adapts Hoppe’s introduction to Rothbard at 100, which also faults Milei for keeping the central bank, expanding the money supply and taking on more IMF debt.
- Stephan Kinsella, “Argentina: 2.1% monthly CPI rise after 3 years of ‘Misesian’ economics” (Aug. 13, 2026). This is July’s figure (about 28% annualized), passed along by Ammous. It’s the roughly 30% inflation the two debaters argue over: Carrino calls it a ten-year low, and Ammous says it proves the printing continues.
- Oscar Grau, “The Downfall of the Spanish Armada of Austro-Libertarianism” (May 26, 2026). Grau describes how Jesús Huerta de Soto and other academics tied to the Mises Institute sold Milei’s government as an “Austro-libertarian revolution.” This is the background to Ammous’s complaint that Austrian ideas were used to sell business as usual.
- Martin Cabrera, “The ‘Austro-libertarian’ Keynesian president strikes again” (Mar. 30, 2026). The government planned to pump in pesos and cut bank reserve requirements to boost consumer spending, which Cabrera calls textbook Keynesianism. Keep it in mind when Carrino calls current monetary policy “very prudent.”
- Kristoffer Mousten Hansen, “Hoppe versus Milei on Central Banking: Breaking Down the Differences,” Mises Wire (Feb. 6, 2025). Hansen rebuts Milei’s hyperinflation argument, calling it a version of the discredited real-bills doctrine, and argues that closing the bank would strengthen the peso. It bears on both Ammous’s “non-negotiable” point and Carrino’s defense of keeping the bank.
- Other posts on Milei at PFS, StephanKinsella.com, and HansHoppe.com
- See Nicolás Antiporovich, “«Argentina necesita lo que Milei prometió»: Saifedean Ammous,” CriptoNoticias (Oct. 30, 2026), in Spanish. [↩]





 Alessandro Fusillo
 Andreas Tögel
 David Dürr
 Doug French
 Fernando Chiocca
 Greg Morin
 Hans-Hermann Hoppe
 Jay Baykal
 Jayant Bhandari
 Jeff Deist
 Jeffrey Barr
 Juan Fernando Carpio
 Ken Yamarashi
 León Isidoro
 Martin Cabrera
 Nick Hoppe
 Oscar Grau
 Peter Wong
 PFS
 scholarium
 Saifedean Ammous
 Sean Gabb
 Sean Ring
 Stephan Kinsella
 Stéphane Geyres
 Thomas Jacob
 Tom DiLorenzo

Follow Us!